



Glass market intelligence helps business evaluators move beyond headline growth figures to assess where demand is real, where capacity is tightening, and where regional risks may reshape investment returns.
From PV glass and architectural applications to high-performance specialty products, this analysis examines the market signals, production constraints, regulatory pressures, and competitive shifts that matter across global regions.
The central conclusion is straightforward: attractive glass demand does not automatically create an attractive manufacturing investment, especially where energy costs, overcapacity, or import competition remain unresolved.
Business evaluators should test every opportunity through three connected questions: what end-market demand is durable, what capacity can actually serve it, and what regional conditions threaten returns.
Start With the Commercial Question, Not the Headline Growth Rate
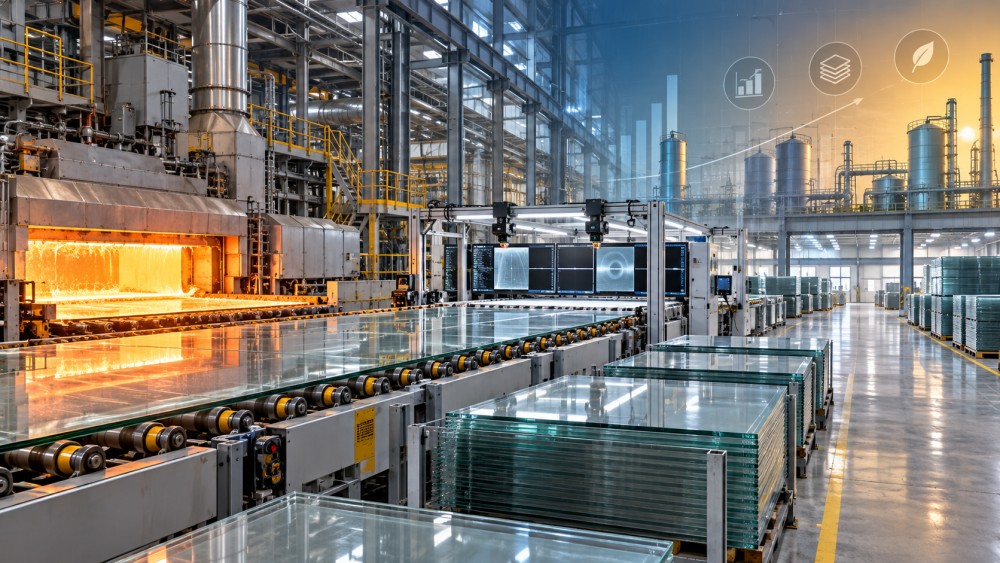
Most glass market reports begin with global consumption forecasts, but evaluators need a narrower answer: which product category will generate profitable, accessible demand during the investment horizon?
Flat glass, container glass, fiberglass, technical glass, and solar glass respond to different demand drivers, operating requirements, customer concentration patterns, and trade exposure levels.
A regional construction rebound may improve architectural glass volumes while doing little for photovoltaic glass, where module supply chains, policy incentives, and export rules carry greater weight.
Likewise, rising food and beverage consumption can support container glass demand, yet local recyclate availability and lightweighting trends may materially change furnace economics.
Glass market intelligence becomes useful when it converts broad market expansion into a realistic revenue pool for a specific plant, product mix, customer segment, and delivery radius.
Evaluators should separate total addressable demand from contestable demand. A market may be large, but incumbent contracts, qualification cycles, logistics costs, and specification barriers can restrict entry.
For capital-intensive projects, the relevant demand figure is usually not national consumption. It is the volume that can be supplied at acceptable margins after transport, tariffs, and customer switching costs.
That distinction is particularly important for commodity flat glass, where freight economics often create regional markets despite apparently global supply availability and widely published capacity figures.
Build Demand Analysis Around End Uses and Leading Indicators
Reliable demand assessment starts with end-use segmentation. Glass consumption should be mapped against the industries that place orders, rather than treated as one homogeneous materials market.
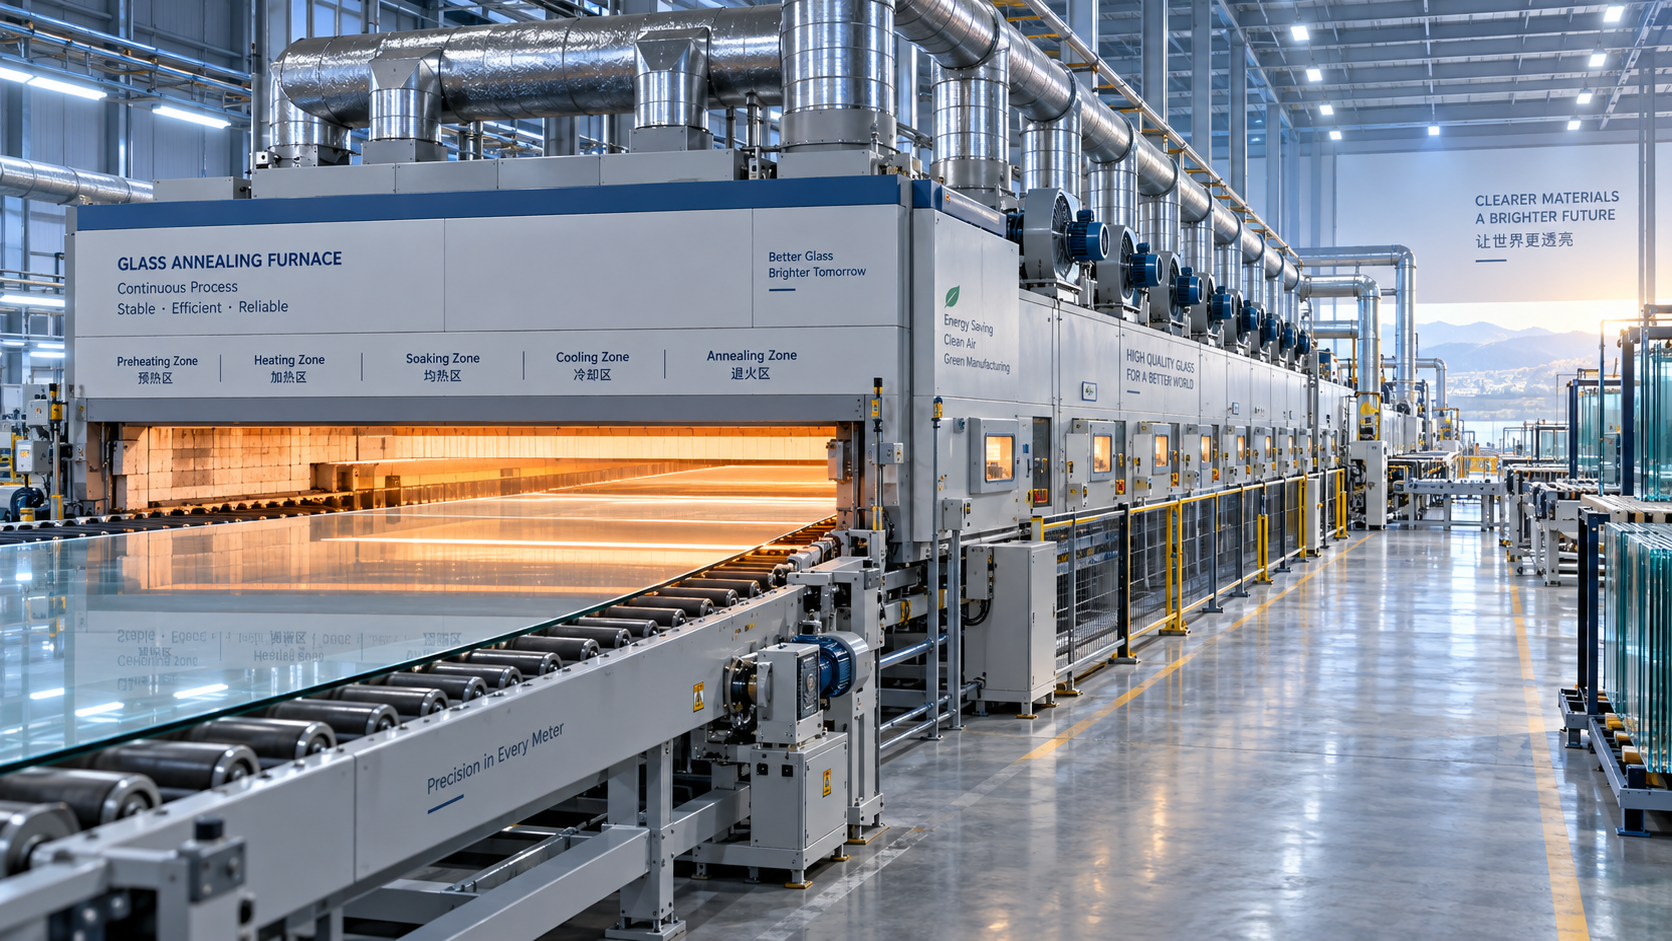
Architectural float glass demand is linked to construction starts, renovation activity, building codes, façade design trends, and local preferences for energy-efficient glazing systems.
Automotive glass depends on vehicle production, replacement demand, export assembly activity, model mix, and growing requirements for acoustic, laminated, heated, and display-integrated glazing.
Solar glass demand follows photovoltaic module output, installation pipelines, domestic-content rules, technology shifts, and the location of downstream module manufacturing rather than electricity demand alone.
Specialty glass requires a different lens. Display, pharmaceutical, laboratory, optical, and electronic applications often have smaller volumes but longer qualification periods and stronger pricing discipline.
Business evaluators should seek leading indicators that precede glass purchasing decisions. Permitting data, project awards, vehicle schedules, module factory announcements, and packaging investments are more actionable than annual consumption totals.
Customer interviews also matter. Procurement teams can reveal whether reported demand reflects firm orders, distributor inventory accumulation, temporary shortages, or genuine changes in technical requirements.
A practical demand model should contain a base case, an upside case, and a downside case. Each should identify the operational trigger behind volume changes.
For example, an upside case for solar glass may assume commissioned module capacity and stable export access, while a downside case assumes price pressure from imported modules.
Assess Capacity as Effective Supply, Not Nameplate Output
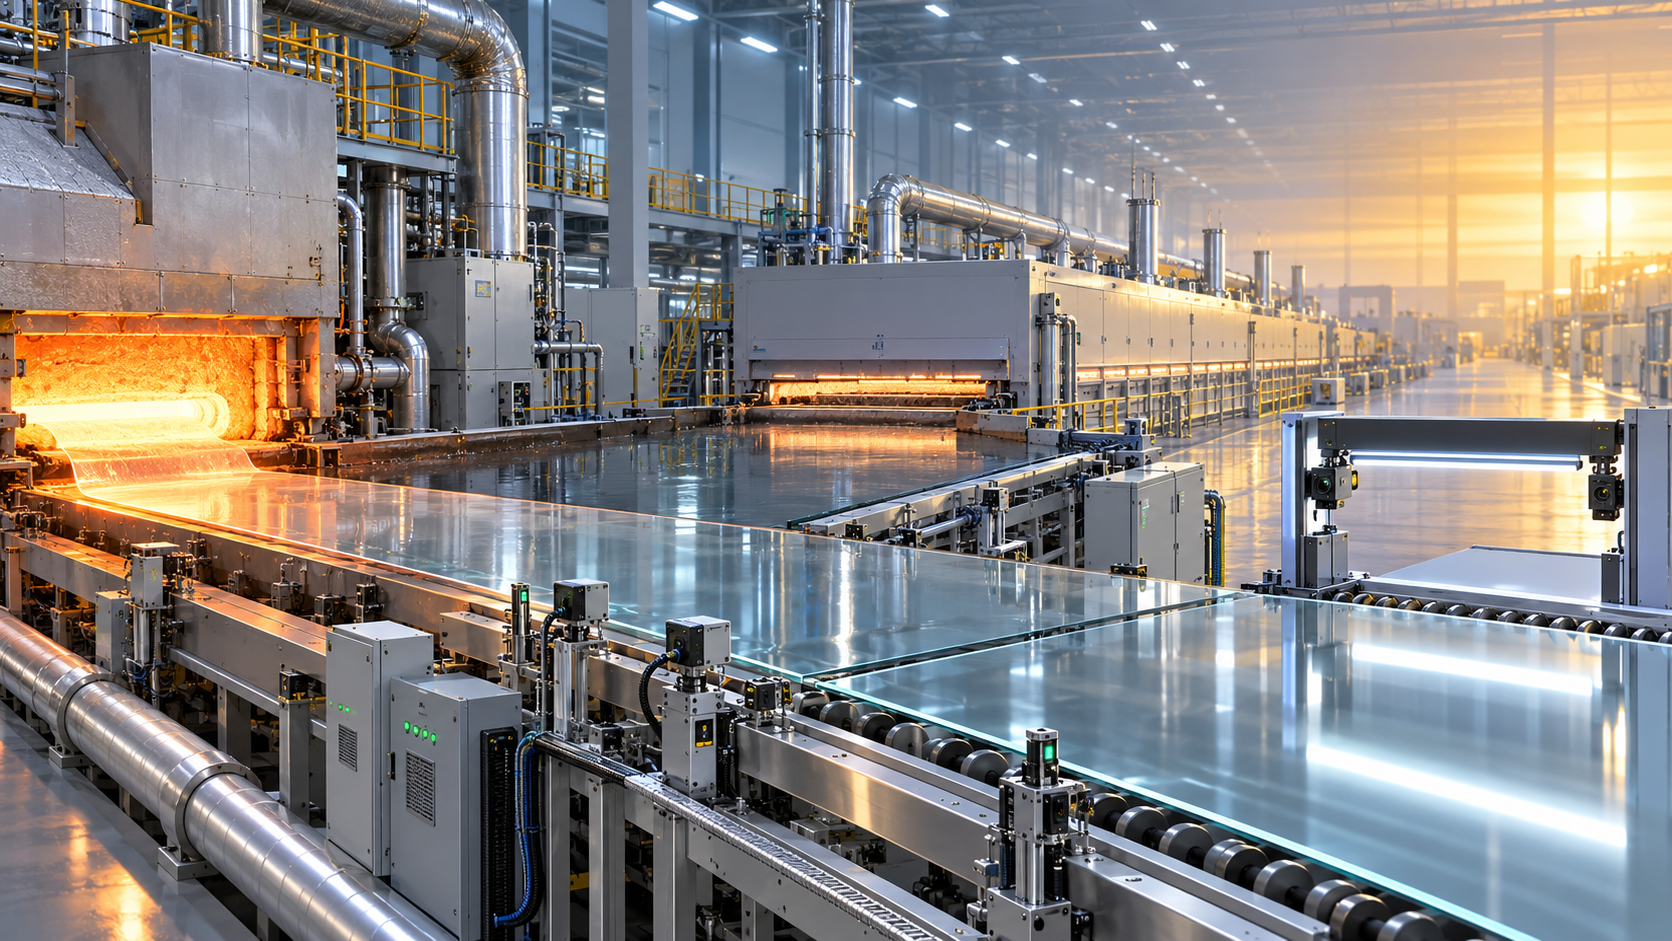
Capacity headlines are frequently misleading because nameplate output rarely equals saleable production. Furnace age, product mix, yield losses, maintenance cycles, and energy constraints reduce effective supply.
Glass manufacturing assets are also difficult to adjust quickly. A furnace cannot always be idled and restarted without major cost, creating prolonged periods of oversupply or shortages.
Evaluators should distinguish between announced projects, equipment-installed projects, hot commissioning projects, and plants consistently producing qualified commercial output. These categories have very different market consequences.
New capacity announcements deserve particular scrutiny in regions with subsidized industrial development, uncertain utility connections, incomplete environmental approvals, or limited access to trained operating personnel.
The timing of furnace rebuilds matters as much as new construction. A major repair can remove meaningful local supply for months and alter bargaining power temporarily.
Capacity analysis should also examine technical substitutability. A line designed for standard clear float glass may not readily supply coated architectural products, thin solar glass, or high-specification automotive grades.
For specialty segments, certification and customer approval can create an effective capacity constraint even when physical furnace capacity appears ample on paper.
Useful glass market intelligence tracks capacity by product capability, geographic reach, operating utilization, furnace condition, and customer qualification status, rather than relying on a single industry total.
A capacity map should include import sources because regional producers may face competitive supply from neighboring countries with lower energy costs or excess domestic output.
Test Energy, Raw Materials, and Carbon Exposure Before Valuing Margins
Energy is often the largest swing factor in glass manufacturing profitability. Natural gas, electricity, oxygen, and carbon costs can change regional competitiveness faster than selling prices.
Evaluators should model energy costs under normal, stressed, and regulated scenarios. Long-term utility contracts deserve review for volume commitments, indexation formulas, interruption rights, and renewal terms.
Fuel flexibility can improve resilience, but it may require capital investment, emissions controls, process redesign, and careful validation of glass quality outcomes.
Raw material analysis should cover silica quality, soda ash availability, limestone, dolomite, colorants, cullet supply, inbound logistics, and supplier concentration.
Cullet deserves special attention because it can lower melting energy requirements and emissions. However, its value depends on collection systems, contamination rates, sorting quality, and color availability.
In container glass, constrained cullet supply can weaken both cost competitiveness and customer sustainability claims. In flat glass, suitable recycled material may be even harder to secure.
Carbon regulation is no longer a peripheral disclosure issue. It can influence operating costs, equipment choices, customer preferences, export access, and the financing terms of major projects.
Decision-makers should examine emissions intensity per tonne, available allowance treatment, future reporting obligations, and exposure to carbon-border mechanisms in destination markets.
A lower-cost furnace can become strategically weaker if its emissions profile restricts sales to multinational customers with formal Scope 3 reduction targets.
Compare Regions Through Risk-Adjusted Economics
Regional growth should be evaluated through risk-adjusted economics, not demand forecasts alone. The best-looking market may carry currency volatility, infrastructure limits, permitting delays, or political uncertainty.
China remains influential across several glass categories because of its scale, technology depth, and export capability. Evaluators must closely monitor domestic demand, capacity discipline, and trade responses.
North America can offer stable demand for energy-efficient building products, packaging, and advanced applications, but labor availability, permitting, and project execution costs may constrain expansion.
Europe offers sophisticated customers and strong decarbonization demand, yet high energy costs, carbon exposure, and uneven construction activity require careful margin testing.
India, Southeast Asia, the Middle East, and selected African markets can present compelling growth opportunities, particularly where urbanization and industrial investment are increasing glass consumption.
Those regions also require deeper due diligence on power reliability, skilled workforce availability, logistics corridors, import competition, financing conditions, and the enforceability of commercial contracts.
Regional analysis should include trade flows rather than treating borders as barriers. Low-cost imports can rapidly reset local prices when shipping routes, tariffs, and currency movements align.
Conversely, antidumping duties, local-content rules, or certification requirements can shelter regional producers, although policy protection should not replace a sound operating-cost position.
A useful regional scorecard combines demand growth, effective capacity, energy economics, trade exposure, regulatory predictability, supply-chain security, and customer credit quality.
Identify Competitive Position Through Customer Economics
Competitor analysis should focus on the reasons customers choose a supplier. Price matters, but consistency, technical service, delivery reliability, certification, and working-capital terms often decide repeat business.
For architectural glass, processors may prioritize coating availability, sheet quality, size consistency, and lead times. For specialty glass, qualification support and defect control can be decisive.
Business evaluators should identify whether the proposed operation will be a cost leader, a regional logistics leader, a technical specialist, or a supplier with protected customer access.
A project without a clear competitive position is vulnerable even in a growing market. Growth can attract new entrants faster than customer relationships can be secured.
Customer concentration requires explicit modeling. Large anchor customers can stabilize utilization, but they may demand price concessions, extended payment terms, or exclusive capacity commitments.
Commercial diligence should therefore test contract duration, minimum volumes, pass-through mechanisms, quality claims history, change-of-control provisions, and customer rights during supply disruptions.
Where no binding customer contracts exist, evaluators should discount projected utilization sharply. Expressions of interest and preliminary discussions are not substitutes for validated sales commitments.
Use a Practical Decision Framework for Investment Reviews
A disciplined review process turns glass market intelligence into an investment decision. Start by defining the target product, intended customers, sales radius, and required annual utilization.
Next, calculate the contestable demand pool using end-market forecasts, customer qualification constraints, incumbent supply relationships, and realistic logistics costs.
Then map effective supply, including local production, likely imports, furnace rebuild schedules, planned capacity, and the technical capabilities of competing lines.
Model margins under multiple energy, raw-material, carbon, freight, and selling-price scenarios. The downside case should reflect conditions that have occurred historically, not merely modest assumptions.
Assess execution readiness separately from market attractiveness. A strong market cannot compensate for an unapproved site, uncertain gas supply, weak engineering control, or insufficient working capital.
Finally, define decision gates. These may include securing customer volume commitments, validating utility pricing, completing environmental approvals, confirming equipment performance guarantees, or reaching a minimum projected return threshold.
This framework is especially valuable for acquisitions. Existing plants may offer customers and operating knowledge, but hidden furnace repair needs or energy contracts can alter value materially.
Conclusion: Focus on Resilience, Not Just Market Size
Effective glass market intelligence does not simply identify fast-growing regions or popular applications. It reveals whether demand can be served profitably, reliably, and defensibly over time.
For business evaluators, the strongest opportunities combine verified end-market demand, constrained effective capacity, manageable energy exposure, credible customer access, and regional conditions that support execution.
Projects should be approached cautiously when utilization depends on uncontracted demand, announced capacity is poorly understood, energy costs remain unhedged, or trade policy drives the economics.
The right conclusion may be to invest, acquire, expand gradually, delay entry, or focus on a higher-value niche. The decision should follow evidence, not market headlines.